
DoorDash Rebound Signal: Analysts See Double-Digit Upside From Here

DoorDash (NASDAQ: DASH) triggered a rebound with its 2026 guidance update, and the upside will run into double-digits. Based on analysts' forecasts, the minimum is 20% at the low end of their range, and the consensus level is more than 40% above the critical support target. While the post-release response was mixed, including three price target reductions to the range’s lower end, the consensus of 36 analysts is a Moderate Buy and not all reduced their targets. Analysts at Bank of America boosted their target to an above-consensus $72, suggesting some conviction remains in the forecast.
DoorDash’s institutional activity is also in alignment with a market bottom. MarketBeat data reveals the group owning more than 90% of the shares, buying on balance for seven consecutive quarters, and activity ramping sequentially to record highs in early 2026. The group may slow the pace of buying as the quarter progresses and share prices advance, but is unlikely to revert to distribution soon. The price forecast is robust enough as it is, and there is potential for an upgrade cycle to form.
DoorDash Accelerates Spending to Accelerate Growth in 2026
Details from the fiscal Q4 2025 earnings release and guidance point to stronger-than-expected results along with increased spending. Spending will be focused on technological rollouts, marketing, new verticals, and density pushes to sustain and accelerate growth. In this environment, outperformance is likely, if not early in the year, then as it progresses, and will drive longer-term sentiment as well. The bad news is that increased spending will cut into the bottom line; the good news is that EBITDA margins are expected to expand, setting the company up for further margin expansion in the years ahead.
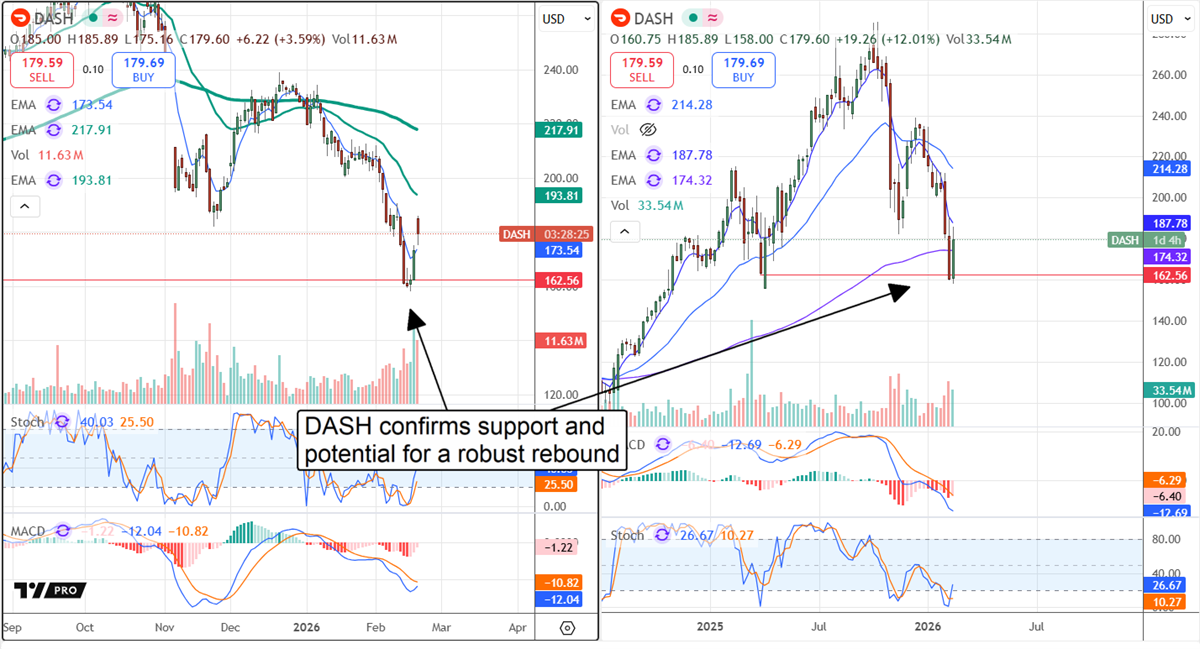
The technical outlook is bullish. The DASH market, which has declined considerably from its peak, has now had sufficient time to reset. The indicators show oversold conditions and a strong chance of a rebound, with stochastic indicators forming bullish crossovers at their lows, and the bearish moving average convergence divergence (MACD) diverging from recent stock price lows. The question is whether the market will follow through on the signal, and the answer is likely to be yes, given the institutional activity and the trend in analysts' sentiment. However, the upswing faces hurdles, potentially causing volatility along the way. The critical targets are near $190 and $215 and will likely be reached before mid-year.
DASH Analysts Look Past Tepid Q4 Results to a More Robust Year Ahead
DoorDash had a weak quarter, at least compared to the anaslyts consensus forecast. The revenue and earnings fell short of MarketBeat’s reported consensus, but are no less strong for it. The $3.96 billion in net revenue is up nearly 40% compared to the prior year, underpinned by a 32% increase in order volume and 39% increase in order value. Growth was seen across the board, with strengths in core markets, but International stands out, outperforming the U.S. by a wide margin as acquisitional integration accelerated business faster than expected.
Margin news is also good. The company widened its GAAP margin and sustained operational quality, leaving the net income up by 51% year over year and adjusted EBITDA in line with revenue at 38%. Free cash flow is the only truly bad news, growing at a slower 17.6% pace, but the softness is offset by growth and increased investment targeting it.
The year-end balance sheet highlights show no red flags and instead provide positive incentives for investors. Cash and asset increases are offset by increased debt and liabilities, but leverage remains low, with total liabilities running about 2x cash and less than 1x equity. The takeaway is that the company is well-capitalized, has solid cash flow, and little encumbrance. It is able to build equity, up 28% for the year, and return capital to shareholders. Capital returns consist entirely of buybacks but are sufficient to reduce the count, providing shareholders with additional leverage each quarter.
DoorDash Risks Don’t Offset the Potential
DoorDash’s risks include competition, regulatory hurdles, and shifting consumer trends, although none pose an immediate threat. While competition is high, the company executes at a high level, leading competitors in growth. Regulatory hurdles are a more pressing problem, which may lead to driver reclassification and a change in business model. However, legislation to that effect is still years in the making, and consumer trends are resilient and could strengthen further. Early reports reveal that 2025 tax refunds are 10% larger than the previous year, a boost for consumers nationwide.
Where Should You Invest $1,000 Right Now?
Before you make your next trade, you'll want to hear this.
MarketBeat keeps track of Wall Street's top-rated and best performing research analysts and the stocks they recommend to their clients on a daily basis.
Our team has identified the five stocks that top analysts are quietly whispering to their clients to buy now before the broader market catches on... and none of the big name stocks were on the list.
They believe these five stocks are the five best companies for investors to buy now...
See The Five Stocks Here
The article "DoorDash Rebound Signal: Analysts See Double-Digit Upside From Here" first appeared on MarketBeat.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Meta (META.US) surged 36% in September: Muse validates AI strategy, market cap targets $2 trillion
Meta's stock is on track to achieve its best monthly performance since July 2013, and is only about a 1% increase away from joining the $2 trillion market cap club.
Consumption stratification intensifies, Costco remains "firmly seated in Diaoyutai"?
Is the market less confident in US Treasury bonds than before?
Up 36% in September! Meta achieves its best monthly performance since 2013, with market value approaching $2 trillion
Since September, Meta's stock price has rebounded significantly. The rapid rise of Muse has reignited market expectations for its AI commercialization. Muse reached 902,000 downloads within six days of launch and is quickly expanding into shopping, travel, and other scenarios. The market is beginning to bet that AI agents could unlock new growth opportunities beyond advertising. However, security and privacy risks, as well as high computing power costs, remain key factors in realizing these expectations.
Crypto prices
More


