
Vale (VALE) Reports 2025 Production Growth, 17% YoY Q4 2025 EBITDA Increase

Vale (NYSE:VALE) is one of the best value stocks to buy now. On February 12, Vale reported its full year 2025 financial and operational performance, exceeding production guidance across all key minerals. Iron ore production rose to 336 million tons, while copper and nickel production saw double-digit jumps of 10% and 11%, respectively. This operational surge translated into a 17% year-over-year increase in pro forma EBITDA for Q4, reaching $4.8 billion. Notably, the base metals division more than doubled its EBITDA contribution, signaling a strategic pivot toward energy-transition materials.
The company achieved major milestones in safety and sustainability, fulfilling its commitment to eliminate all high-risk emergency level 3 dams by the end of 2025. Financial discipline remained a core theme, as Vale reduced its net debt to $15.6 billion and achieved significant cost reductions; nickel all-in costs fell by 35%, and iron ore all-in costs were reduced to $54 per ton.
To unlock further value, Vale (NYSE:VALE) launched the Novo Carajás program to double copper output and continues to focus on operational reliability in its nickel business, aiming for cash flow neutrality by the end of 2026.
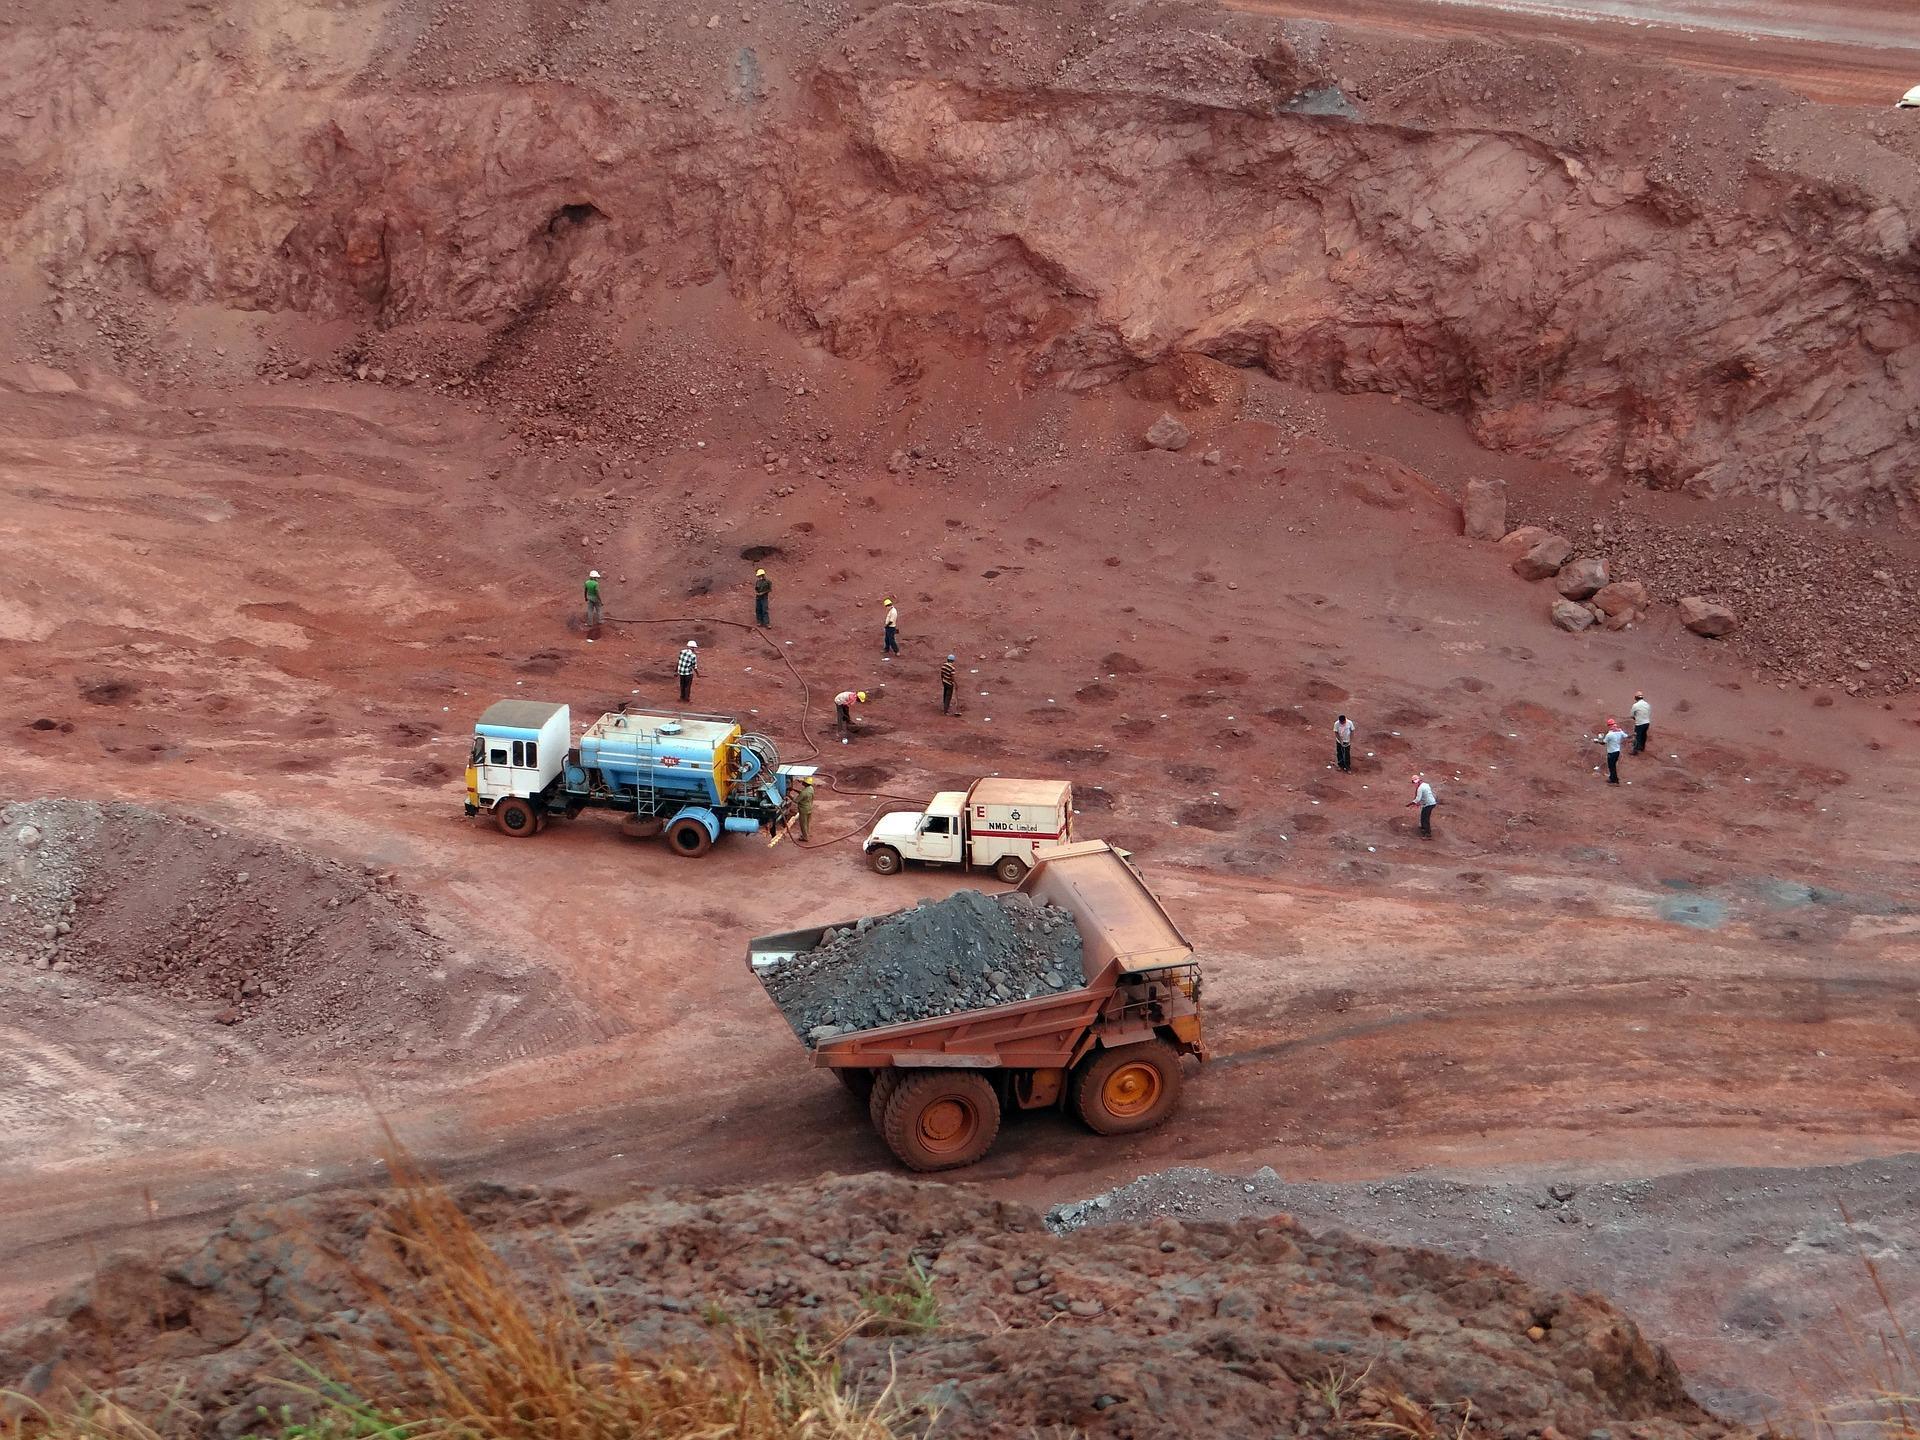
Vale (NYSE:VALE), together with its subsidiaries, produces iron ore and nickel in Asia, the Americas, Europe, and internationally. It operates through two segments: Iron Solutions and Energy Transition Materials.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
This time, will U.S. Treasury bonds crash U.S. stocks?
Bloomberg strategist Simon White warns that the recent rise in US Treasury yields is shifting from a "benign" increase driven by interest rate expectations to a disorderly surge fueled by expanding term premium. Market analysts note that higher long-term interest rates will simultaneously push up US stock valuation discount rates and corporate financing costs, intensifying liquidation pressure on highly leveraged assets. If interest rates above 5% become the new norm, US stock valuations will face ongoing compression pressure.
Eurosystem Launches Blockchain Platform for Tokenized Asset Settlements
SUI Price Sets Up for Bigger Rally as Weekly SAR Flips Bullish — $1.50 Next?
Crypto prices
More


