
The Canary in the Coal Mine of Private Credit: From Blue Owl to the Illusion of Semi-Liquid Products

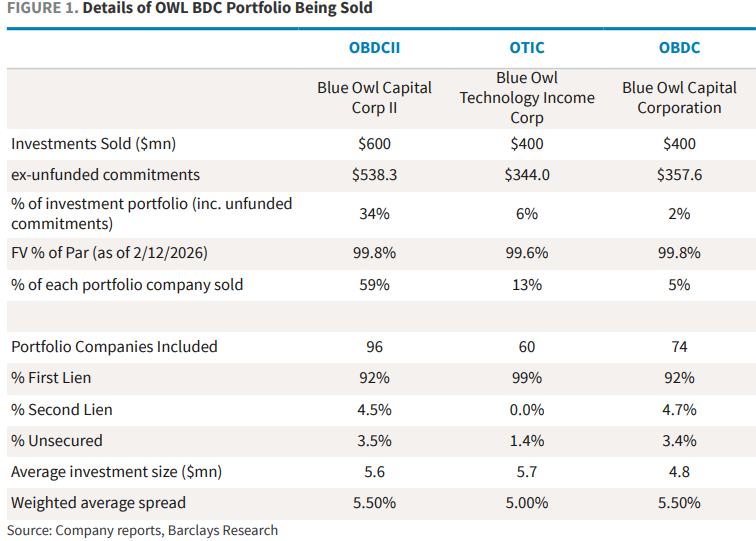
On February 18, Blue Owl, a global leading alternative asset management company, announced that its retail private credit vehicle OBDCII will permanently terminate its quarterly redemption arrangement, and instead return capital to investors in installments via loan repayments, asset sales, and special dividends. At the same time, in order to provide investors with the promised liquidity and to repay debt, Blue Owl announced the combined sale of approximately $1.4 billion in direct loan assets across three BDC vehicles (OBDCII, the listed BDC fund OBDC, and the technology income fund OTIC), with about $600 million of the sales coming from OBDCII—accounting for roughly 34% of its investment portfolio.
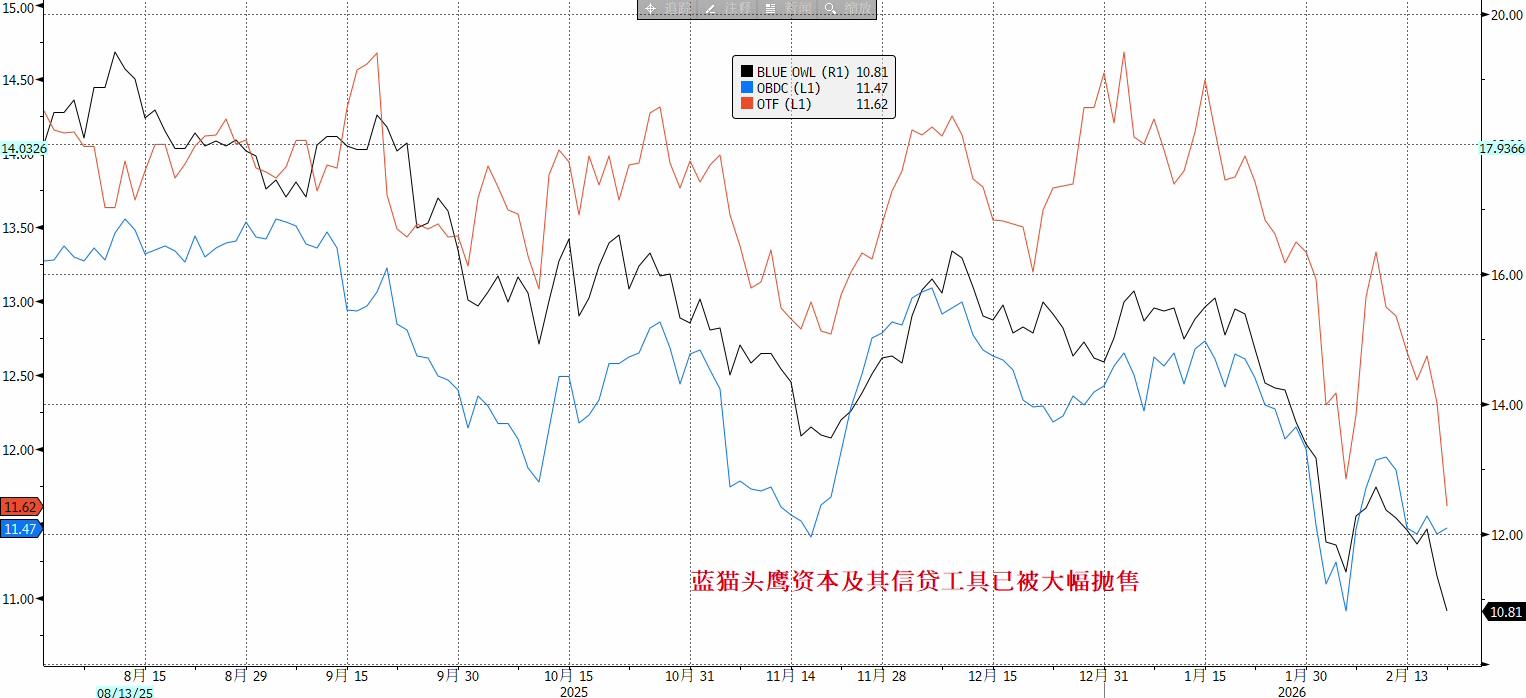
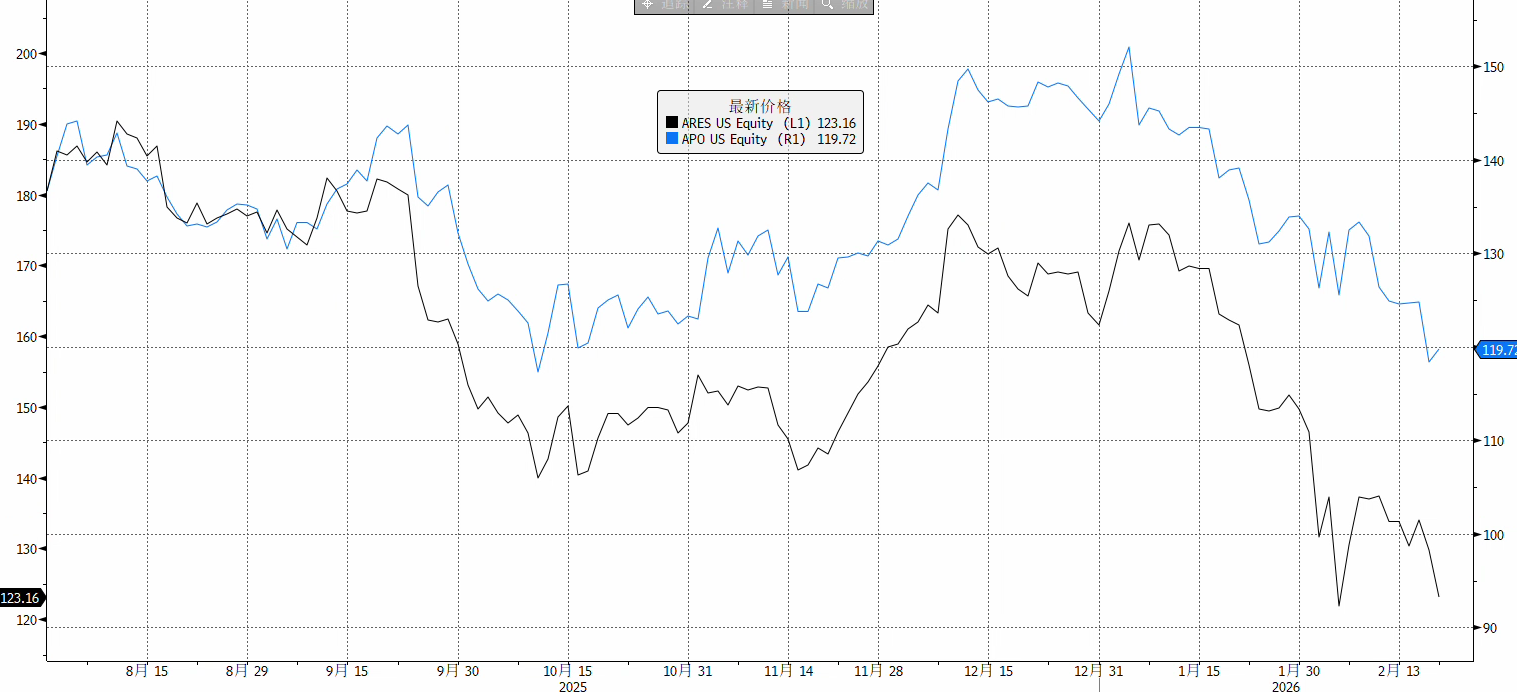
The market reacted strongly to this news. On February 19, Blue Owl's stock price dropped nearly 10% intraday, hitting its lowest point in two and a half years, and ultimately closed down 5.9%. Panic quickly spread across the entire alternative asset management sector, with peers such as Ares, Apollo, Blackstone, and KKR generally falling by 3%-6%; European firms CVC and Partners Group also declined.
Even more shocking, on February 21, hedge fund Saba proposed to acquire Blue Owl-related BDC shares at a 20%-35% discount to the latest NAV, publicly challenging the fairness of the fund's reported valuations. Although the offer is not mandatory, its symbolic significance lies in this: there is now a significant gap between the liquidity price offered by the secondary market and the NAV disclosed by the managers. Meanwhile, structured notes linked to Blue Owl plummeted in price, with one note issued by Citigroup falling below 50% of par value.
Overall, the Blue Owl incident is by no means a mere liquidity management failure of a single company. It has directly burst the illusion of semi-liquid products in the $3 trillion private credit market in recent years. This event may become the "canary in the coal mine" moment for private credit, potentially a replay of the August 2007 BNP Paribas fund freeze incident—a prelude to the onset of the financial crisis.
Trust Crisis in the Semi-Liquid Product Model
The Blue Owl incident touches upon the most vulnerable link in private credit: the sustainability of the semi-liquid product model. These products promise regular redemptions (such as quarterly) to retail investors, while the underlying assets are non-public loans with terms of 5-10 years. The core problem lies in:
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
Federal Reserve approves stress test reform by a 6-1 vote: Capital requirement volatility halved, sole dissenting vote warns of reduced resilience
The Federal Reserve has officially approved two final rules aimed at increasing transparency and reducing capital requirement volatility by approximately 50%. The new regulations will seek public comments on stress test scenarios and will calculate the capital buffer based on the average of the results from two consecutive years of testing. This averaging mechanism will take effect in 2028. The reforms are the result of years of negotiation within the banking sector and have been welcomed by industry groups. However, critics such as Governor Barr warn that the reforms will weaken the constraints of stress testing and reduce the overall resilience of the banking system.

Metals fade as long yields offset cooler inflation, lower Fed odds - Kitco PM Report
Bitwise brings NEAR to Wall Street – But the chart isn’t impressed
Synopsys and OpenAI reach AI chip design partnership, stock price surges over 7%
Synopsys has signed a multi-year legally binding agreement with OpenAI to jointly develop GPT-Synopsys, a model specifically trained and fine-tuned for chip design tasks. OpenAI will pay Synopsys a subscription fee for tool licensing, and both parties will share revenue based on improvements in chip design achieved by customers using the product.
Crypto prices
More


