
Here's What Investors Must Know Ahead of Vulcan's Q4 Earnings

Vulcan Materials Company VMC is scheduled to release fourth-quarter 2025 results on Feb. 17, before the opening bell.
In the last reported quarter, the company’s adjusted earnings and total revenues topped the Zacks Consensus Estimate by 6% and 1.7%, respectively. Also, year over year, both metrics increased 27.9% and 14.4%, respectively.
Vulcan’s earnings topped the consensus mark in three of the last four quarters and missed on the remaining one occasion, with an average surprise of 13%.
How Are Estimates Placed for VMC Stock?
The Zacks Consensus Estimate for fourth-quarter earnings per share (EPS) has declined to $2.13 from $2.16 over the past 30 days. The estimated figure indicates a decline of 1.8% from the year-ago quarter.
The consensus estimate for total revenues is pegged at $1.94 billion, indicating 4.9% year-over-year growth.
Vulcan Materials Company Price and EPS Surprise
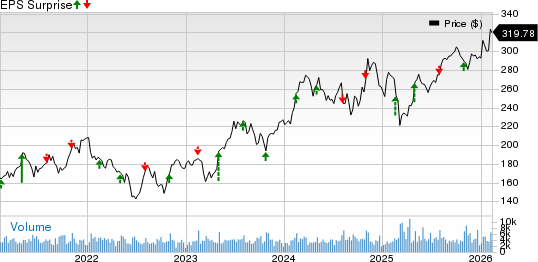
Vulcan Materials Company price-eps-surprise | Vulcan Materials Company Quote
Factors Likely to Shape Vulcan’s Q4 Results
Revenues
During the fourth quarter, Vulcan’s top-line performance is expected to have gained on the back of incremental aggregates pricing and volume growth, reflecting healthy public construction and private nonresidential activities. Besides, favorable weather conditions, especially in the South, are expected to have added to the growth. Acquisitions completed on both coasts also added to revenue scale, while backlogs in both public and private projects gave better visibility, creating a strong pipeline of demand to support top-line expansion.
Notably, the company’s focus on its two strategic disciplines, the Vulcan Way of Selling and the Vulcan Way of Operating, is likely to have offered additional support in the fourth quarter. Through these initiatives, VMC ensures to maintain operational excellence while maintaining work value.
The Zacks Consensus Estimate for revenues from the Aggregates (78.2% of the third quarter of 2025 total revenues) and Concrete (10.4% of the third quarter of 2025 total revenues) business segments is pegged at $1.55 billion and $198 million, reflecting year-over-year growth of 5.2% and 20.7%, respectively. Conversely, the consensus mark for revenues from the Asphalt mix (18.2% of the third quarter of 2025 total revenues) segment is pegged at $317 million, indicating 3.1% downturn year over year.
The Zacks model expects unit shipment volume for Aggregates and Concrete to increase year over year to 55,521 tons and 1,125 tons, up from 53,900 tons and 900 tons, respectively. The shipment volume for Asphalt mix in the fourth quarter is expected to decline to 3,332 tons from 3,400 tons in the year-ago quarter.
Earnings & Margin Trends
Vulcan’s bottom line is likely to have been hurt in the fourth quarter due to cost inflation and lingering tariff uncertainties in the market. Besides, the other ongoing macro headwinds and pressured end markets like single-family housing are expected to have restricted bottom-line growth despite price increases.
What the Zacks Model Unveils for VMC
Our proven model does not predict an earnings beat for Vulcan this time around. The combination of a positive Earnings ESP and a Zacks Rank #1 (Strong Buy), 2 (Buy) or 3 (Hold) increases the odds of an earnings beat. This is not the case here.
VMC's Earnings ESP: Vulcan has an Earnings ESP of -1.58%. You can uncover the best stocks before they’re reported with our Earnings ESP Filter.
VMC's Zacks Rank: The stock currently carries a Zacks Rank of 3. You can see the complete list of today’s Zacks #1 Rank stocks here.
Recent Construction Releases
Masco Corporation MAS posted mixed fourth-quarter 2025 results, wherein the adjusted earnings surpassed the Zacks Consensus Estimate, while net sales missed the same. Both metrics tumbled on a year-over-year basis.
The quarter’s performance was largely in line with expectations as the company operated through a changing geopolitical and economic backdrop. It began restructuring actions to simplify operations, lower costs and reduce headcount. Masco also announced the integration of Liberty Hardware into the Delta Faucet business to better align brands and capabilities. For 2026, Masco expects demand across global repair and remodel markets to remain steady. Sales are projected to be flat to slightly higher on a currency-adjusted basis, with performance likely to outpace the broader market.
Jacobs Solutions Inc. J reported stellar first-quarter fiscal 2026 (ended Dec. 26, 2025) results, with adjusted earnings and revenues beating the Zacks Consensus Estimate and growing year over year.
Jacobs' quarterly results reflect stronger performance in the life sciences, data center, semiconductor, water and transportation sectors, alongside increased demand for digital consulting services, bolstering the quarter’s uptrend. With the announcement of acquiring the remaining stake in PA Consulting and favorable market fundamentals, Jacobs is optimistic about its performance in the remaining fiscal 2026. Adjusted net revenues are now expected to grow year over year between 6.5% and 10%, with adjusted EPS expected to be between $6.95 and $7.30.
Weyerhaeuser Company WY reported mixed fourth-quarter 2025 results, wherein its earnings topped the Zacks Consensus Estimate, but net sales missed the same. Meanwhile, on a year-over-year basis, both the top and bottom lines decreased.
Weyerhaeuser’s fourth-quarter results were impacted by persistent market headwinds across key markets, characterized by softened pricing and volatile demand dynamics. Despite these challenges, the company continued to optimize its portfolio through disciplined, capital-efficient transactions. Looking ahead, Weyerhaeuser is well-positioned to navigate the current environment, supported by a strong balance sheet and flexible capital allocation framework as it executes its refreshed 2030 strategy to drive growth and capitalize on durable long-term demand fundamentals.
Disclaimer: The content of this article solely reflects the author's opinion and does not represent the platform in any capacity. This article is not intended to serve as a reference for making investment decisions.
You may also like
AI demand drives TSMC to accelerate capacity expansion, 2nm monthly production aims for 120,000 wafers by year-end
According to reports, industry giants such as Apple, Nvidia, and AMD have collectively increased their orders by 10% to 20%, directly boosting TSMC's 2nm monthly production capacity to 120,000 wafers by the end of the year, which exceeds the previous estimate by more than 20% and brings forward the 2027 target by two years. For the first time in history, five factories will ramp up production simultaneously, and the annual compound growth rate of capacity from 2026 to 2028 will reach as high as 70%.
Long-term US Treasury Sell-off Continues! 10-Year Treasury Yield Breaks 5.2% Again, “AI Boom vs. Rising Financing Costs” Narrative Showdown Intensifies
On Monday, oil prices rose and US Treasury bonds were sold off again as former US President Donald Trump rejected Iran's latest proposal to reopen the Strait of Hormuz, heightening concerns about inflation.
Banks Have Been Earning Effortlessly from Idle Funds for Years—Will AI Agents Change Everything?
For years, banks have profited from customers' idle funds, but AI agents may be about to change this situation.
Goldman Sachs: US stocks are showing a "strong index, weak confidence" pattern; catch-up rally may become the main theme of the next phase
Goldman Sachs stated that the current U.S. stock market is showing an unusual pattern: while index performance is strong, investor confidence remains weak. This suggests that the market still has further upside potential, and stocks that previously lagged behind leading AI stocks may soon experience a catch-up rally.

Crypto prices
More


